Long-Term Care Benefits 2026: New Insurance & Government Support
Understanding long-term care benefits in 2026 is crucial for assessing new insurance options and government support programs to secure future care needs.
As we look towards 2026, the landscape of long-term care benefits 2026 is undergoing significant transformations. Planning for future care needs is more critical than ever, with new insurance options emerging and government support programs adapting to meet the demands of an aging population.
Understanding the Evolving Landscape of Long-Term Care
The concept of long-term care encompasses a wide range of services designed to assist people with chronic illnesses, disabilities, or other conditions that limit their ability to perform everyday activities. These services can be provided at home, in the community, or in various types of facilities. The evolving nature of healthcare, combined with demographic shifts, means that understanding these changes is paramount for effective planning.
In the United States, the need for long-term care is projected to rise dramatically. This increase is driven by an aging baby-boomer generation and advancements in medical science that allow people to live longer, often with multiple chronic conditions. Consequently, both private and public sectors are recalibrating their offerings to address this growing demand.
The Shift in Care Delivery Models
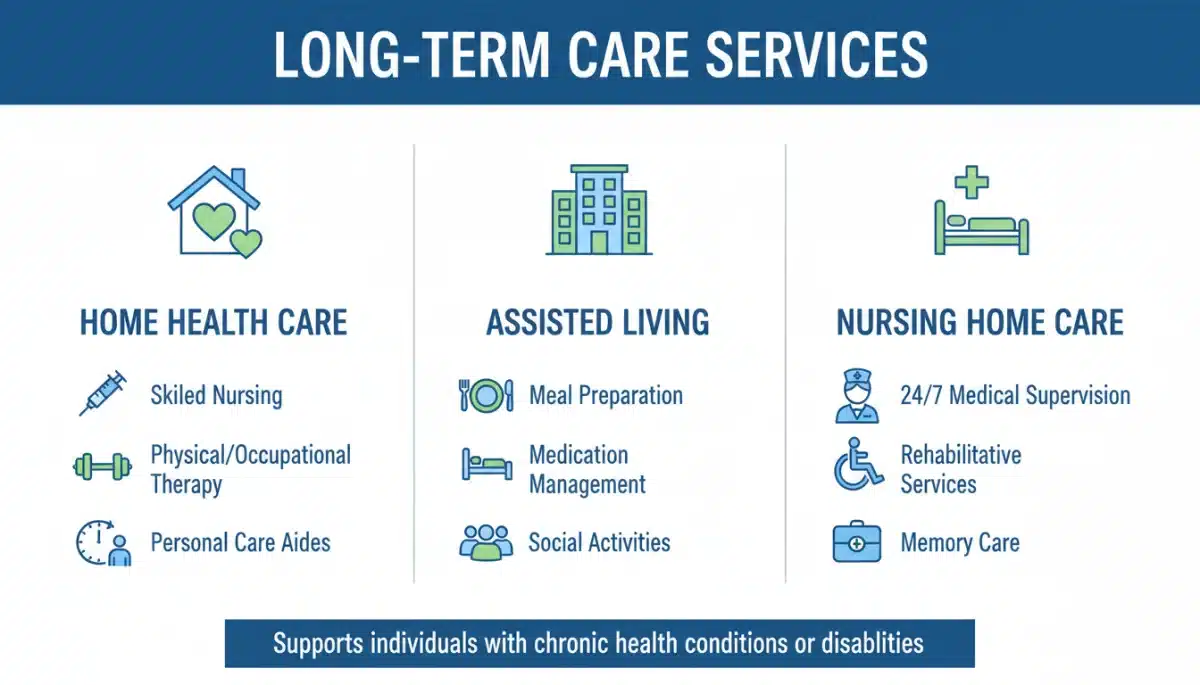
Historically, long-term care was often synonymous with nursing homes. However, 2026 sees a continued shift towards more personalized and home-based care options. This preference for aging in place reflects a desire for comfort and familiarity, as well as being a more cost-effective solution in many cases.
- Home Health Aides: Providing assistance with daily activities like bathing, dressing, and eating in the comfort of one’s home.
- Assisted Living Facilities: Offering a balance of independence and support for those who need some help but not constant medical care.
- Adult Day Care Services: Providing supervised care in a community setting for individuals who need assistance or supervision during the day.
- Nursing Homes: Offering 24-hour skilled nursing care for individuals with complex medical needs.
The move towards diverse care models highlights the importance of flexible long-term care solutions. Families and individuals now have more choices, but this also means a greater need for informed decision-making regarding which option best suits their specific circumstances and financial capabilities.
Ultimately, navigating the evolving long-term care landscape means staying informed about the various services available and how they integrate with insurance and government programs. This proactive approach ensures that individuals can access the care they need without facing undue financial burdens.
New Private Insurance Options for Long-Term Care in 2026
As the demand for long-term care grows, the private insurance market is responding with innovative products designed to offer more flexibility and broader coverage. In 2026, consumers will find an array of new insurance options that aim to address previous shortcomings and provide more attractive solutions for future care planning.
Traditional long-term care insurance (LTCI) policies have faced challenges in recent years, including rising premiums and complex benefit structures. However, insurers are now developing hybrid policies and more customizable plans that integrate with other financial products, making them more appealing to a wider audience.
Hybrid Life Insurance with Long-Term Care Riders
One of the most significant trends in private long-term care coverage is the rise of hybrid policies. These policies combine life insurance or annuities with long-term care benefits, offering a ‘use it or lose it’ solution that many find more attractive than standalone LTCI.
- Guaranteed Premiums: Many hybrid policies offer guaranteed premiums, providing financial predictability.
- Death Benefit: If long-term care benefits are not fully utilized, a death benefit is paid to beneficiaries.
- Cash Value: Some policies accumulate cash value that can be accessed if needed.
These hybrid options provide a safety net, ensuring that policyholders or their beneficiaries receive a benefit regardless of whether long-term care services are needed. This integrated approach simplifies financial planning by combining two essential needs into a single product.
Additionally, new standalone LTCI policies are being designed with greater flexibility in benefit periods, daily maximums, and inflation protection. Consumers can now tailor policies more precisely to their anticipated needs and budget, making long-term care insurance a more viable option for a broader demographic.
Exploring these new private insurance options is a critical step for anyone planning for long-term care. Understanding the benefits, limitations, and costs associated with each type of policy will enable individuals to make informed decisions that align with their financial goals and future care preferences.
Government Support Programs and Updates for 2026
Beyond private insurance, government programs play a crucial role in providing support for long-term care. In 2026, several federal and state initiatives are being updated or introduced to better address the financial and logistical challenges of long-term care for eligible individuals. These programs often serve as a vital safety net for those who cannot afford private insurance or have exhausted their personal resources.
Medicaid remains the primary payer for long-term care services in the United States, particularly for individuals with limited income and assets. However, states are continually refining their Medicaid programs to expand access to home and community-based services (HCBS), reducing reliance on institutional care.
Medicaid Expansion and HCBS Waivers
Many states are expanding their Medicaid programs to cover a broader range of long-term care services, often through Home and Community-Based Services (HCBS) waivers. These waivers allow states to offer services outside of institutional settings, promoting independence and quality of life.
- Expanded Eligibility: Some states are adjusting income and asset limits to allow more individuals to qualify for Medicaid long-term care benefits.
- Increased HCBS Funding: Federal incentives are encouraging states to shift more funding towards home and community-based care, reducing the need for nursing home placement.
- Personal Care Services: Medicaid may cover personal care services, such as assistance with daily living activities, provided by a caregiver.
Furthermore, discussions at the federal level continue regarding potential universal long-term care programs or enhanced tax incentives for long-term care expenses. While no definitive federal program has been enacted to mirror social security for long-term care, the ongoing dialogue suggests a growing recognition of the need for broader public support.
Veterans also have access to specific long-term care benefits through the Department of Veterans Affairs (VA). These benefits can include nursing home care, assisted living, and home healthcare, depending on service-connected disabilities and financial need. It is essential for veterans and their families to explore these specific programs.
Staying informed about government support programs and their eligibility requirements is vital. These programs can provide substantial financial relief and access to essential care for those who qualify, complementing or even replacing private insurance coverage.
Navigating Eligibility and Application Processes
Understanding the criteria for eligibility and the application processes for both private long-term care insurance and government support programs can be complex. In 2026, while some processes are streamlined, others may require careful attention to detail and significant documentation. Proactive planning is key to successfully accessing these crucial benefits.
For private long-term care insurance, eligibility typically involves a health underwriting process. Applicants will need to provide medical history, undergo physical examinations, and answer detailed health questionnaires. The younger and healthier an applicant is, the more likely they are to secure a policy with favorable rates.
Government programs, particularly Medicaid, have strict financial and medical eligibility criteria. These often include income and asset limits, as well as a functional assessment to determine the level of care needed. The ‘look-back period’ for asset transfers is a critical consideration for Medicaid planning, as it can affect eligibility if assets were transferred within a certain timeframe before applying.
Key Steps in the Application Process
Whether applying for private insurance or government aid, a structured approach can help ensure a smooth process. Gathering all necessary documentation beforehand is crucial.
- Assess Your Needs: Determine the type and level of care you anticipate needing.
- Research Options: Explore both private insurance and government programs relevant to your situation.
- Gather Documentation: Collect medical records, financial statements, and other required paperwork.
- Seek Professional Advice: Consult with financial advisors or elder law attorneys specializing in long-term care.
- Submit Applications: Complete all forms accurately and submit them within designated timeframes.
The application process for government programs can be lengthy, often requiring patience and persistence. It is advisable to start this process well in advance of when care might be needed. For private insurance, comparing quotes from multiple providers can help secure the best coverage at the most competitive rates.
Successfully navigating eligibility and application processes requires diligence and foresight. By understanding the requirements and preparing thoroughly, individuals can significantly improve their chances of securing the long-term care benefits they need.
The Financial Implications of Long-Term Care Planning
The financial burden of long-term care can be substantial, often exceeding what many families anticipate. In 2026, the costs associated with various care settings continue to rise, making strategic financial planning an indispensable component of preparing for future needs. Without adequate planning, individuals may face devastating out-of-pocket expenses that can quickly deplete savings and assets.
The average annual cost of long-term care varies significantly by location and type of service. For instance, nursing home care can cost upwards of $100,000 per year, while home health aide services, though generally less expensive, still represent a considerable ongoing expense. These figures underscore the importance of having a robust financial strategy in place.
Strategies for Funding Long-Term Care
There are several approaches individuals and families can take to fund long-term care, each with its own advantages and considerations. A multi-faceted strategy often provides the most comprehensive protection.
- Personal Savings and Investments: Utilizing retirement accounts, savings, and other investments is a common method, though it can quickly deplete resources.
- Long-Term Care Insurance: Private policies can cover a significant portion of costs, protecting personal assets.
- Medicaid: For those who meet strict income and asset requirements, Medicaid can cover most long-term care expenses.
- Veterans Benefits: Eligible veterans can access a range of services and financial aid for long-term care.
- Reverse Mortgages: For homeowners, a reverse mortgage can convert home equity into cash for care expenses, though it has implications for heirs.
The decision of how to fund long-term care should be made in consultation with financial advisors who specialize in elder care planning. They can help assess an individual’s financial situation, risk tolerance, and long-term goals to recommend the most appropriate funding mechanisms.
Understanding the financial implications and exploring various funding strategies are crucial steps in ensuring that long-term care needs can be met without jeopardizing financial security. Proactive financial planning offers peace of mind and greater control over future care decisions.
Future Trends and Innovations in Long-Term Care
Looking ahead to 2026 and beyond, the long-term care sector is poised for continued innovation, driven by technological advancements, evolving consumer preferences, and policy changes. These future trends promise to reshape how care is delivered, accessed, and funded, offering both new opportunities and challenges for individuals and policymakers alike.
One prominent trend is the increasing integration of technology into care delivery. Telehealth services, remote monitoring devices, and AI-powered assistance are becoming more prevalent, enabling individuals to receive care and support in their homes more effectively and efficiently. This technological shift can enhance independence and reduce the need for institutional care.
Technological Advancements in Care
Technology is revolutionizing long-term care, making it more accessible and personalized. From smart home devices to advanced medical sensors, these innovations are improving the quality of life for many.
- Telemedicine Platforms: Facilitating remote consultations with healthcare professionals, reducing the need for in-person visits.
- Wearable Health Devices: Monitoring vital signs, activity levels, and detecting falls, providing real-time data to caregivers.
- Smart Home Technology: Assisting with daily tasks, medication reminders, and enhancing safety within the home environment.
- Robotics: Exploring the use of robots for companionship, assistance with physical tasks, and even basic personal care.
Beyond technology, there is a growing emphasis on preventive care and wellness programs aimed at delaying or reducing the need for intensive long-term care. Public health initiatives and private sector programs are focusing on promoting healthy aging, including exercise, nutrition, and mental well-being.
Policy discussions are also likely to continue evolving, with potential for new federal or state incentives for long-term care planning, further expansion of home and community-based services, and efforts to address the caregiver shortage. The future of long-term care will undoubtedly involve a blend of innovative solutions and supportive policies to meet the needs of an aging society.
By staying abreast of these future trends and innovations, individuals can better anticipate changes in long-term care options and adjust their planning strategies accordingly, ensuring they are well-prepared for whatever the future holds.
| Key Aspect | Brief Description |
|---|---|
| Evolving Care Models | Shift from institutional care to diverse home and community-based services, offering more personalized options. |
| New Private Insurance | Introduction of hybrid policies (life insurance/annuity with LTC riders) and customizable standalone LTCI plans. |
| Government Programs | Medicaid expansion and increased focus on Home and Community-Based Services (HCBS) waivers. |
| Financial Planning | Crucial for mitigating high costs; involves personal savings, insurance, and understanding eligibility for aid. |
Frequently Asked Questions About Long-Term Care Benefits 2026
In 2026, key changes include a greater emphasis on hybrid private insurance policies combining life insurance with long-term care riders, expanded state-level Medicaid programs focusing on home and community-based services, and technological advancements enhancing care delivery and monitoring at home. These shifts aim to offer more flexible and accessible care options.
Hybrid long-term care policies integrate long-term care benefits with life insurance or annuities. If you need long-term care, the policy pays out for those services. If you don’t use all the long-term care benefits, a death benefit is paid to your beneficiaries, or the policy may offer a cash value. This structure aims to reduce the ‘use it or lose it’ concern of traditional LTCI.
Generally, Medicare does not cover most long-term care, such as assistance with daily activities, if that’s the only care you need. It primarily covers skilled nursing care or home health care for a limited time after a hospital stay. For extensive long-term care, individuals typically rely on private insurance, Medicaid, or personal funds.
Medicaid is the largest public payer of long-term care services in the U.S. for individuals who meet specific income and asset requirements. In 2026, many states are expanding their Medicaid Home and Community-Based Services (HCBS) waivers to allow more people to receive care in their homes or communities rather than in institutions.
The best time to start planning for long-term care is typically in your 50s or early 60s. Applying for private long-term care insurance when you are younger and healthier often results in lower premiums and a higher likelihood of approval. Early planning also allows more time to build savings and explore all available options without pressure.
Conclusion
The landscape of long-term care benefits in 2026 is dynamic, reflecting an increasing need for adaptable and comprehensive care solutions. From innovative private insurance products like hybrid policies to evolving government support programs emphasizing home and community-based services, individuals have more options than ever to consider. However, navigating these choices requires proactive engagement, thorough research, and often, professional guidance. Understanding eligibility criteria, financial implications, and future trends is paramount to securing adequate care and maintaining financial stability in later life. By planning ahead, individuals and families can ensure they are well-prepared to meet future long-term care needs effectively.
Autor